
Could the home you bought years ago be the reason your next move is more possible than you think?
Very possibly. For many homeowners, the conversation in 2026 is no longer just about what mortgage rates are doing. It is about the equity already sitting inside the home they own, what that equity can do for the next purchase, and whether their current house still fits the life they are living today.
Your First Home Was Supposed To Do A Job

I think people sometimes put a lot of pressure on the idea of a “forever home.”
Your first home does not have to be the house you stay in for 30 years to have been a great decision. Maybe it gave you a foothold in the market. Maybe you fixed it up. Maybe you refinanced. Maybe you simply made your payments month after month while values changed around you.
That counts.
Nationally, Cotality reported that the average mortgaged homeowner had about $310,500 in home equity in the first quarter of 2026. Obviously, that is an average, and your number could be dramatically different, but it tells us something important: a lot of homeowners have more financial flexibility than they realize.
So before you decide that moving up is “too expensive,” find out what you are actually working with.
The 2026 Market Has Created An Interesting Trade-Off

Here is where things get more interesting.
Buyers have more choices than they did a year ago. Across the Northwest MLS service area, active listings in July were up 19.8% year over year. King County inventory was up 23.7%, and Snohomish County was up 34.7%. That means the home you want to buy may be easier to find than it was during the ultra-competitive years.
At the same time, we are not sitting in some giant buyer’s market where sellers have no leverage. NWMLS reported 3.74 months of inventory in July, still below the four-to-six-month range generally considered balanced.
Translation?
You may have more room to shop for your next home while still owning something buyers want.
That is a MUCH more useful conversation than simply asking, “Is this a good market?”
Because the real question is whether this market works for both sides of your move.
Starter Homes Still Have A Job To Do
The original idea behind a starter home is pretty simple. You get into the market, build equity over time, and eventually use that position to help you move forward.
And even though starter-home inventory has improved since the worst of the shortage, it is still constrained nationally. Realtor.com reports there are roughly 300,000 fewer affordable listings than before the pandemic. That tells you smaller and more attainable homes are hardly sitting around with nobody interested.
Now, Puget Sound does not behave exactly like a national chart. Seattle, Renton, Bellevue, Tacoma, Everett, Kitsap, and the communities in between can behave VERY differently depending on price point, property type, commute patterns, and condition.
This is exactly why I would never tell someone, “Starter homes are in demand, so just list it.”
Nope.
You still need to know what buyers are paying for your kind of house in your particular market.
Equity Changes The Math On Your Next Purchase
This is the part homeowners often miss.
Let’s say your next home is substantially more expensive than your current one. Looking at the new home’s price alone can make the move feel impossible pretty quickly.
But your purchase price is not the whole equation.
If you sell your current home and walk away with meaningful equity, some of that money could potentially become your next down payment. A larger down payment can reduce the amount you need to finance, which matters quite a bit when mortgage rates are still elevated. Freddie Mac’s 30-year fixed rate was 6.71% as of September 3, 2026.
I would much rather have you look at the real numbers than talk yourself out of moving based on a rate headline.
What is your likely sale price? What do you owe? What are your selling costs? What might you realistically net? How does that change the payment on the next property?
THAT is the math that matters.
Do Not Automatically Spend Your Equity On The House You Are Leaving
Here is another place where sellers can get themselves into trouble.
You discover you have a lot of equity, so suddenly the temptation is to remodel everything before selling.
New kitchen! New bathroom! New floors! Let’s make it perfect!
Hold on.
In this 2026 market, buyers have more inventory to compare, which means condition and pricing absolutely matter. But that does not mean every improvement gives you the money back.
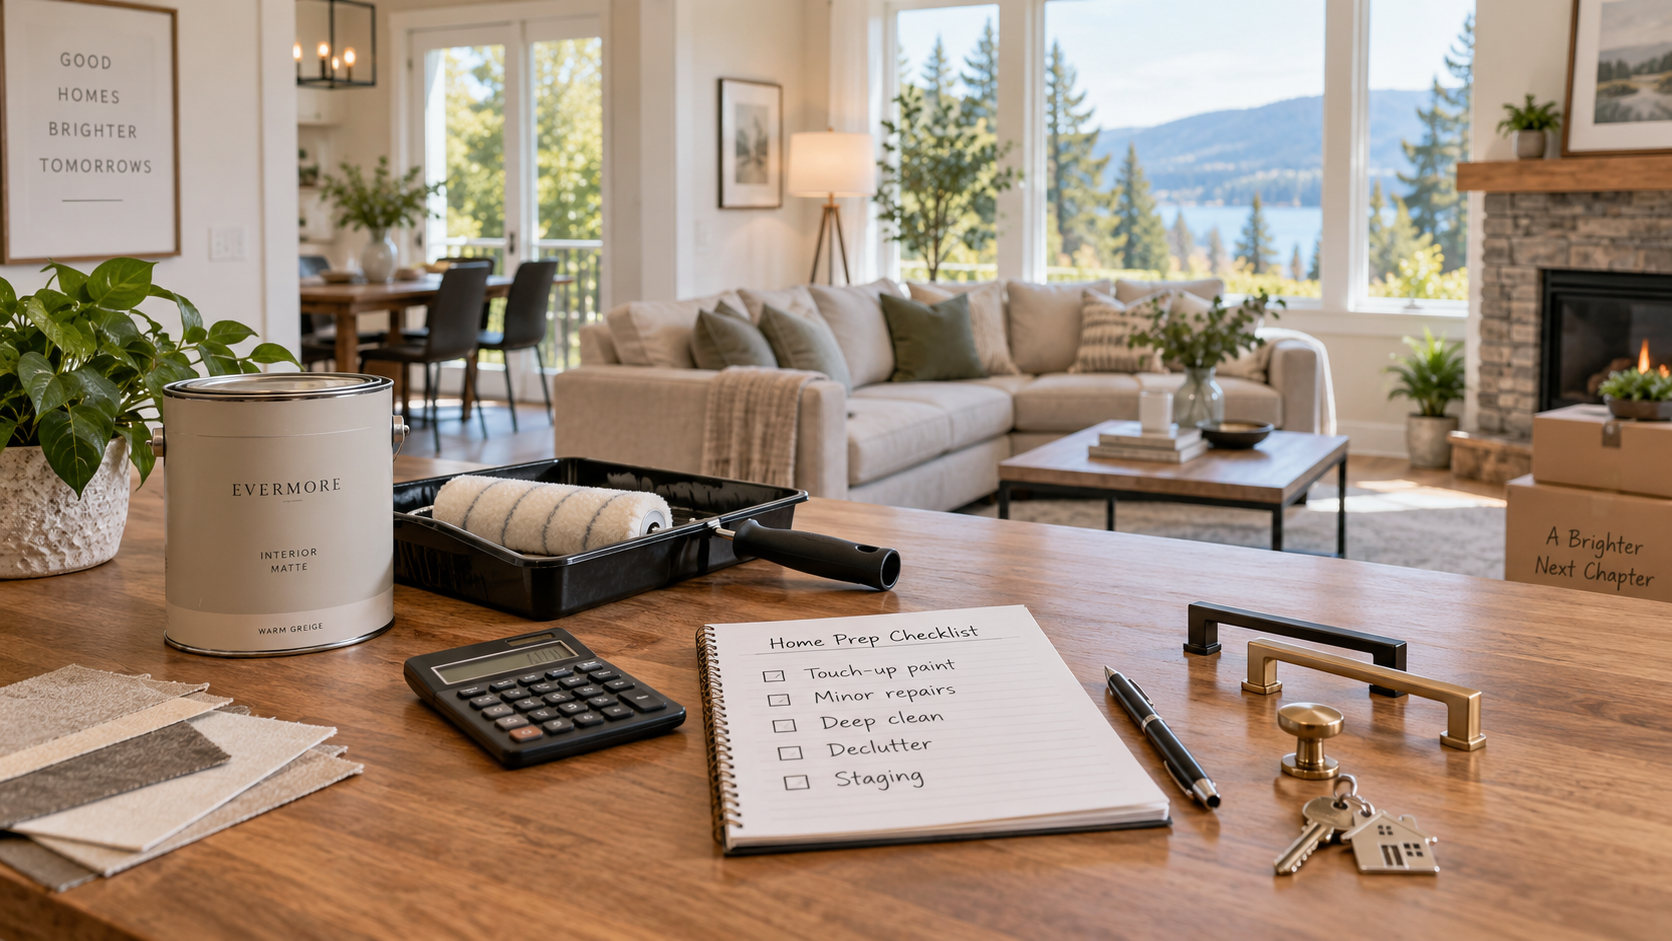
Sometimes $5,000 strategically spent on paint, landscaping, lighting, cleaning, minor repairs, and presentation does far more for the sale than a $50,000 remodel.
And sometimes a house should simply be priced correctly and sold in its existing condition.
This is why I am such a big believer in doing the evaluation before you start hiring people and writing checks. My job is not to help you spend the most money getting ready to sell. It is to help you decide where spending money actually makes sense.
The Move-Up Seller Has More Choices Than A Few Years Ago
This may be the biggest opportunity in the current market.
A few years ago, many homeowners had a very legitimate concern: “Great, I can sell my house. Where am I supposed to go?”
Today, inventory is substantially better across much of Washington. That does not mean every property is easy to buy, but you may have more negotiating room, more time to evaluate options, and more choices than you had during the pandemic-era frenzy.
That can create some interesting strategies.
You might sell first and negotiate additional time before moving. You might identify your replacement-home market before listing. You might structure the sale and purchase together. Or you may discover that the equity position is strong enough that you have options you simply did not know existed.
There is not one magic formula here.
There is a sequence that works for your finances, your house, and whatever you are trying to accomplish next.
Final Takeaway
Your first home may have done exactly what you needed it to do.
It gave you somewhere to live, yes. But it may also have quietly built the financial foundation for your next chapter.
With homeowner equity still substantial, more inventory available across Puget Sound, and buyers having more choices in 2026, this is not a market where I would recommend making assumptions based on headlines alone.
Before deciding you are stuck because rates are higher or the next house costs more, run the numbers on the house you already own.
You may find out that “someday” is a lot closer than you thought.
Want To Know What Your Home Could Make Possible?
If your current house is starting to feel like the place you started rather than the place you want to stay, I would be happy to help you figure out the numbers.
Book a free 15-minute consultation with Reba Haas, REALTOR®:
https://calendly.com/teamreba/free-15-minute-consultation

